Texas Manufactured Housing Market Report - Sales Data & Analysis
Rob Ripperda
October
First Read
October is only about 48% titled at this point, but we can use installation reports to fill the gap. Installers’ Form-T filings reach TDHCA within days of the install, and a home’s installation tends to land a few days before its recorded transfer of ownership date.
Blending October’s titles issued to date with its installation reports points at roughly 1,320 new home sales (± 130) for the month.
The plot below shows how this method has scored so far. Installations ran well ahead of titles in June and July, as they did a year earlier, so the summer misses on the plot may be a seasonal pattern the blended model can’t account for until a second year confirms it. The First Reads for August and September have held up much better, each within about 45 homes of where those months now look to settle.
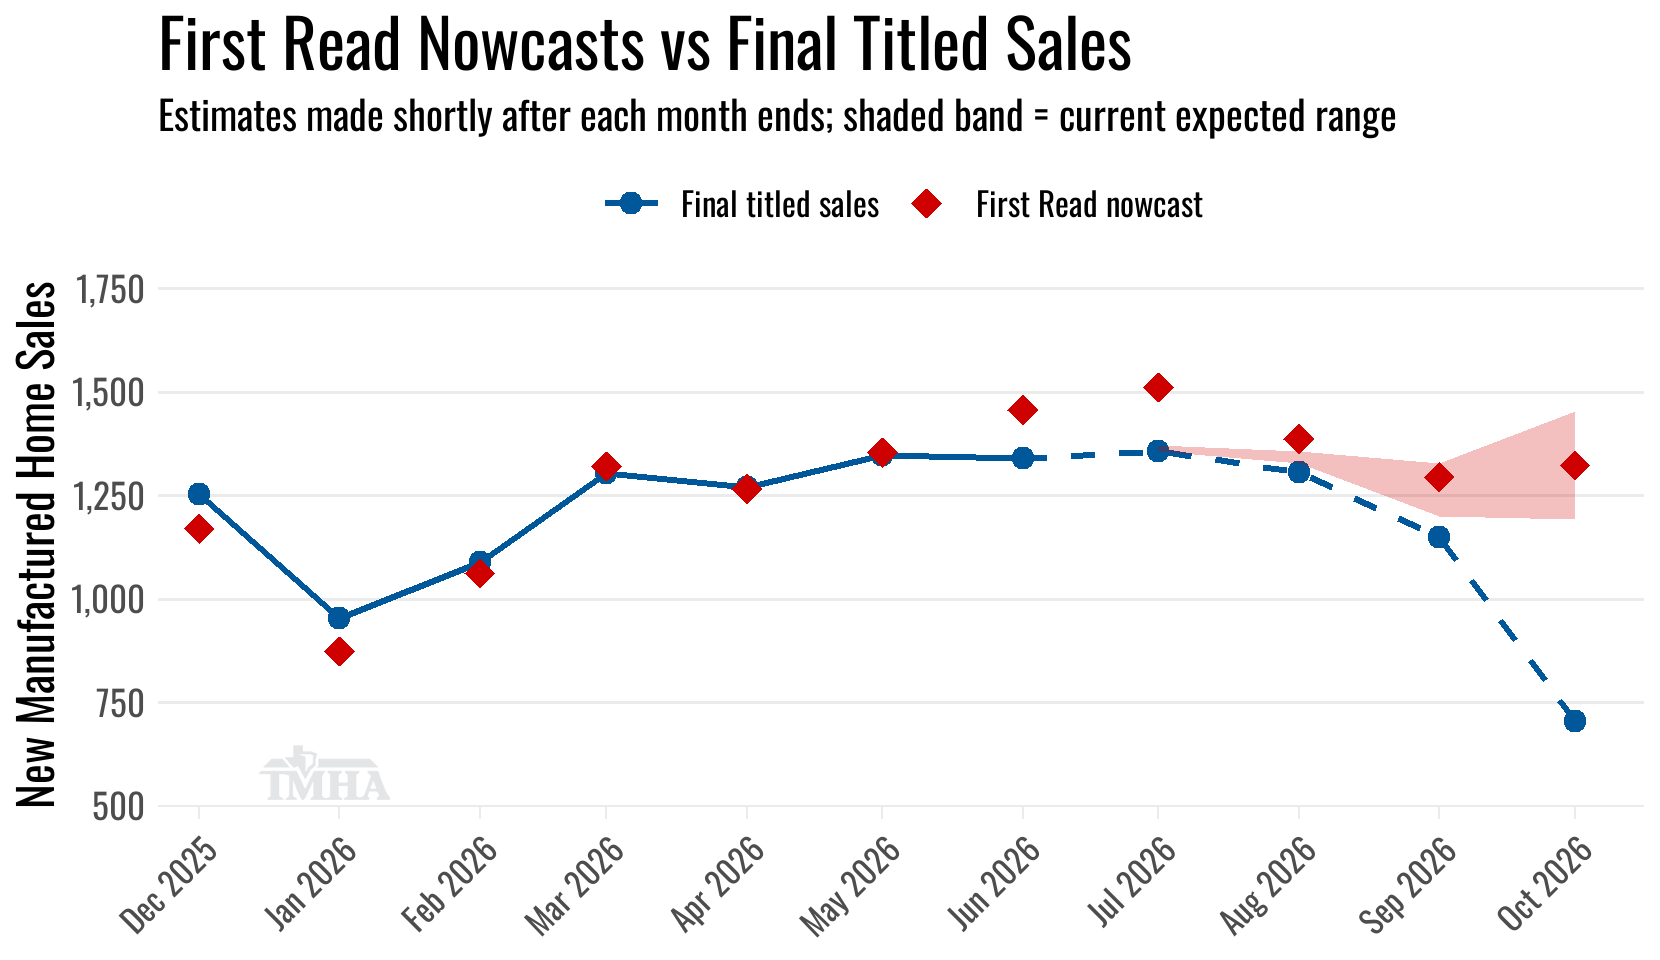
Note: Every diamond is the model’s First Read for that month. Months on the solid line are old enough for their totals to be effectively final. For the months still accumulating titles, the dashed line traces the titles actually issued so far and the shaded band shows the range where each is currently expected to settle, incorporating everything reported since its First Read.
September
Early Look
New manufactured home sales for September 2026 titled to date are so far down a seasonally-adjusted 3% from the previous month and are running 1.3% below September of 2025. September of 2025 settled at 1,288 homes, an easier comparison than August’s 1,479, and with last year’s faster titling now fully in the base the year-over-year reading is close to apples to apples.
About 91% of a sale month’s eventual total is already on the books at this point in the reporting cycle. That puts September on pace to settle near 1,260 new home sales (± 60) once the remaining titles are issued. That would land within about 1.9% of September of 2025’s final total of 1,288, a figure that sits inside the expected range.
As the plot below shows, September’s early count is running just below last year’s line at the same point.
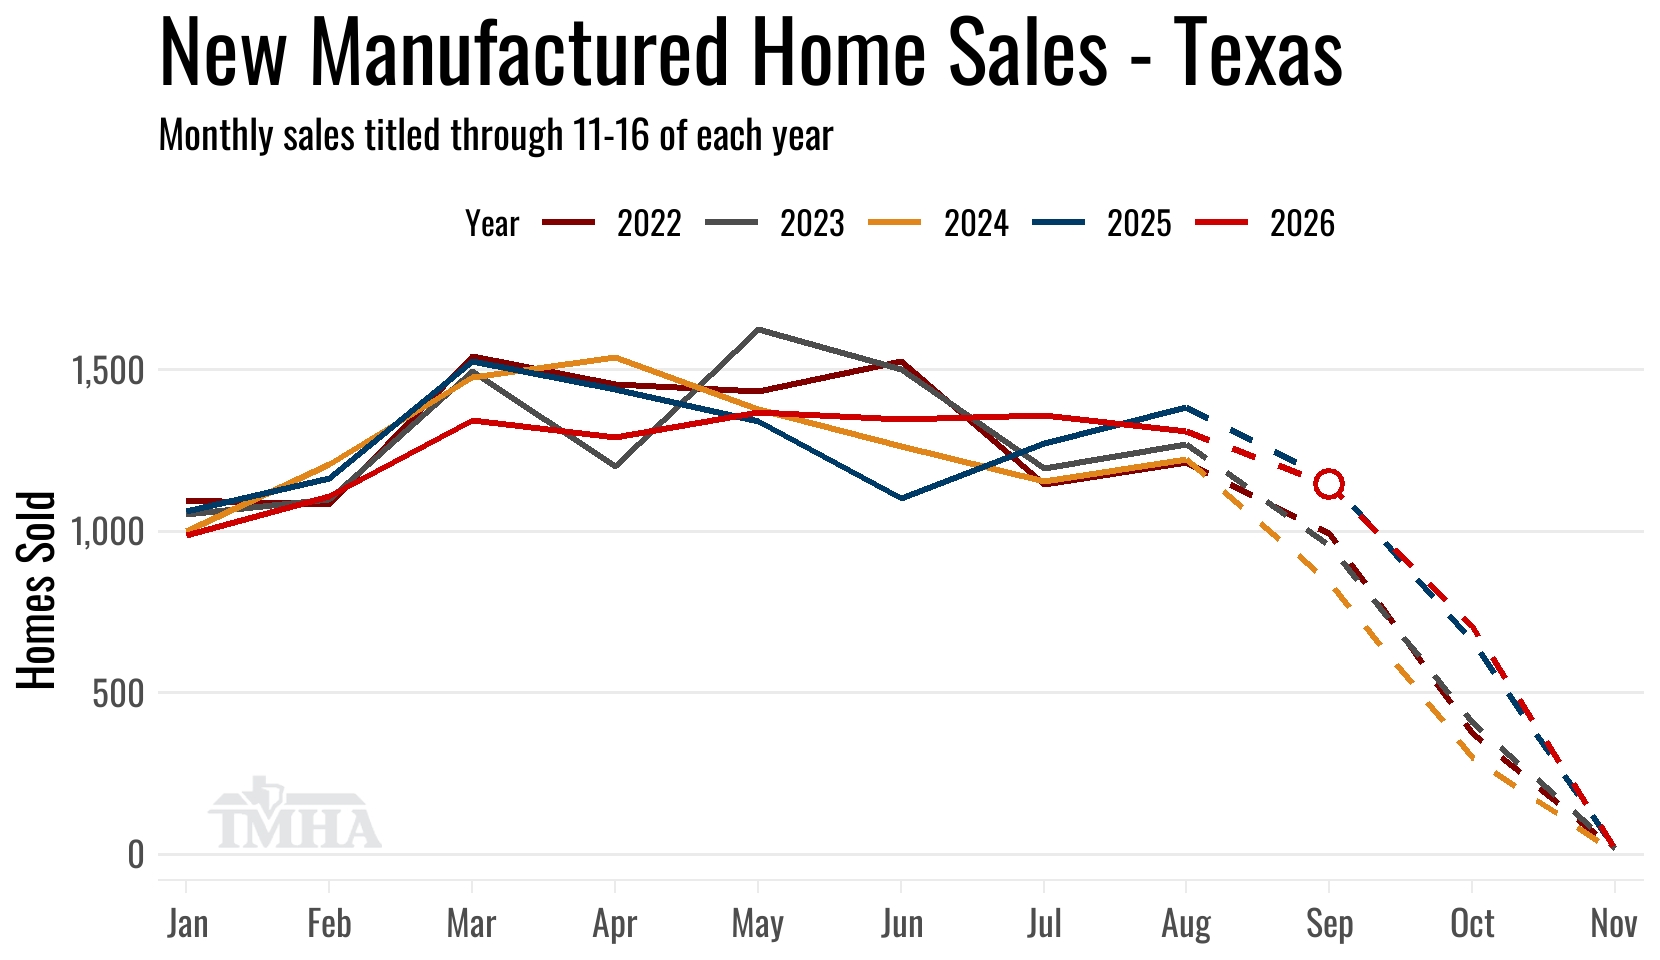
Solid lines represent months for which the on-time titling window has closed. Dashed lines are preliminary months for which titles are still being counted toward the reported total.
The comparisons in the table below are based on where the previous month’s numbers were when originally reported on one month ago.
| New Sales | Singles | Multis | Total |
|---|---|---|---|
| Total for September: | 405 | 739 | 1,144 |
| Change from August (Raw %): | -10.2% | -8.5% | -9.1% |
| Change from August (Raw Units): | -46 | -69 | -115 |
| Change from August (SA %): | -5.6% | -4.4% | -3% |
| Change from September of 2025 (%): | -13.8% | 7.3% | -1.3% |
| Change from September of 2025 (Units): | -65 | 50 | -15 |
TMHA Member’s Retailer Annual Sales Totals Report
August
Titled on Time
New home sales for August titled to date were down a seasonally adjusted 5.1% from the previous month and are down 5.4% on the raw total from August of 2025.
August’s 1,307 homes sold slipped from July’s 1,327 but made it four straight on-time report months above 1,300. Single-section sales edged up from July while multi-section sales eased, and both ran behind August of 2025, singles by 3% and multis by 7%.
With August roughly 97% complete at publication, expect the month to settle near 1,340 new home sales (± 10) as the last titles are issued.
That settled estimate would land about 9% below August 2025’s final total of 1,479. August of 2025 was the largest month of last year’s second half, with faster titling already in place, so this is the toughest year-over-year comparison in the cycle. The comparisons ease from here: September through November of 2025 settled between 1,134 and 1,322 homes.
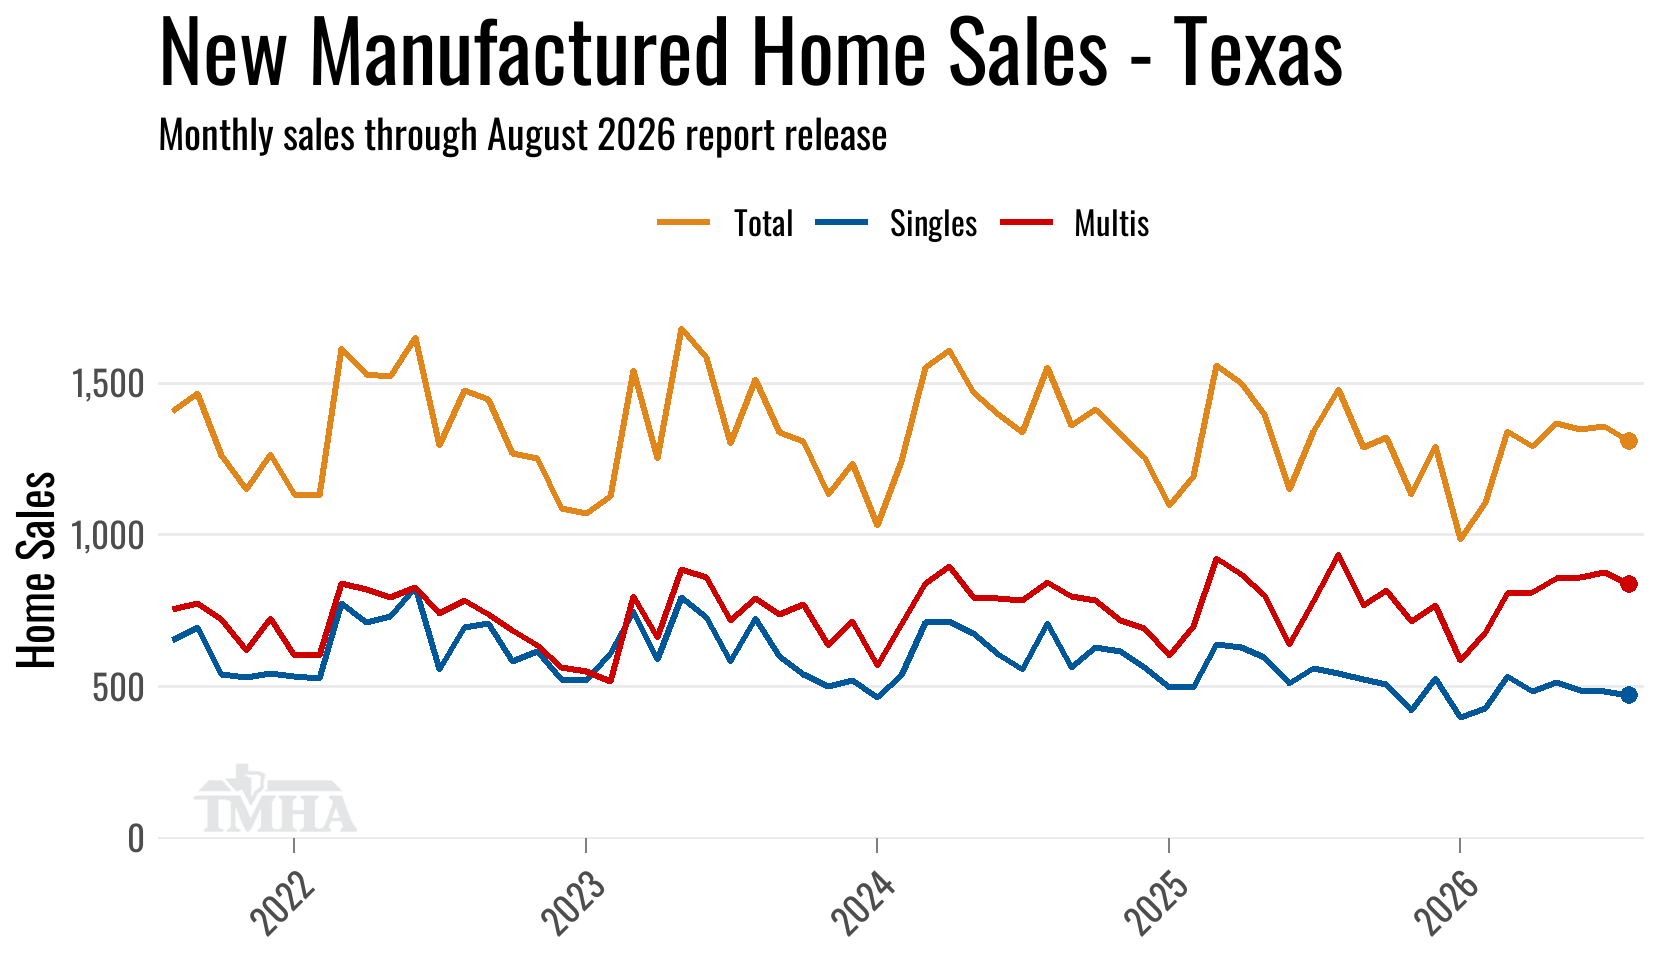
While the plot above contains revised totals for previous months the comparisons in the table below are based on where the previous month’s numbers were when released one month ago.
| New Sales | Singles | Multis | Total |
|---|---|---|---|
| Total for August: | 471 | 836 | 1,307 |
| Change from July (Raw %): | 2.2% | -3.5% | -1.5% |
| Change from July (Raw Units): | 10 | -30 | -20 |
| Change from July (SA %): | 1% | -4% | -5.1% |
| Change from August of 2025 (%): | -3.3% | -6.6% | -5.4% |
| Change from August of 2025 (Units): | -16 | -59 | -75 |
TMHA Member’s Retailer Monthly Sales Totals Report
Titled Installation Location Trends
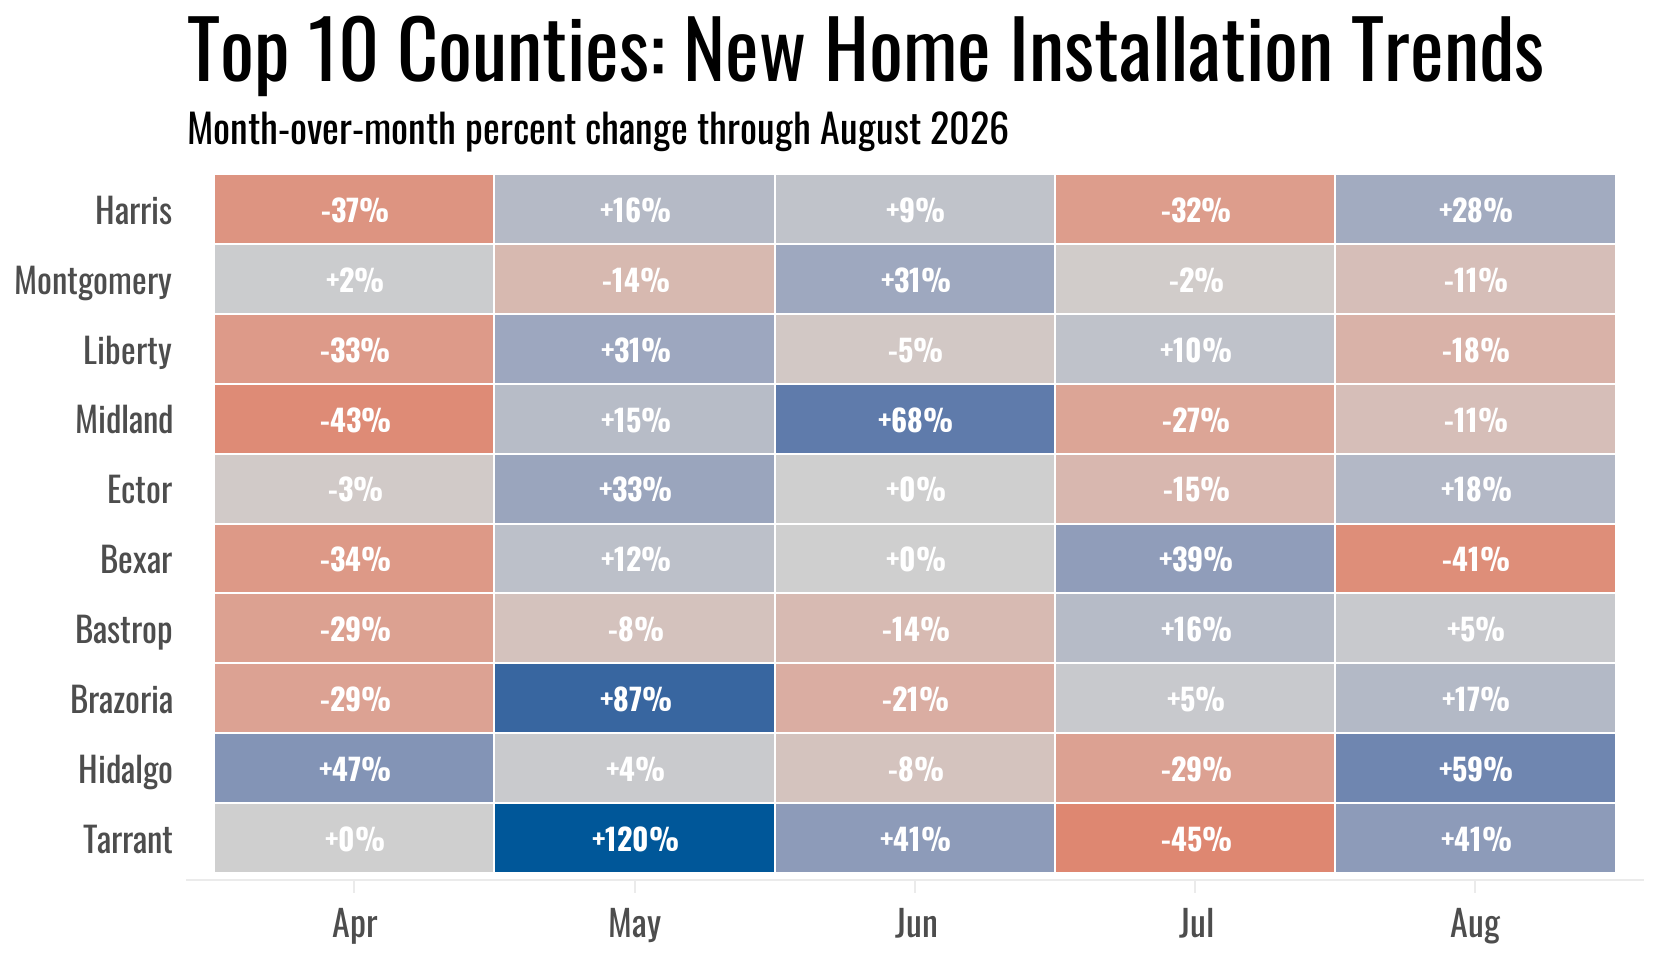
Here are the month-over-month changes for the top 10 counties for new home sales over the past five on-time report months, ranked by their total placements across that span.
August reversed much of July. Harris rebounded 28%, to 41 homes, tying Montgomery for the top spot, Hidalgo jumped 59%, Tarrant 41%, and Ector (18%), Brazoria (17%) and Bastrop (5%) also gained. The other four slipped: Bexar gave back all of July’s jump (down 41%, to 23 homes, its lowest month in the window), Liberty fell 18%, and Montgomery and Midland each eased 11%.
TMHA Member’s Retailer Annual Sales Total per County Report
Annual Totals
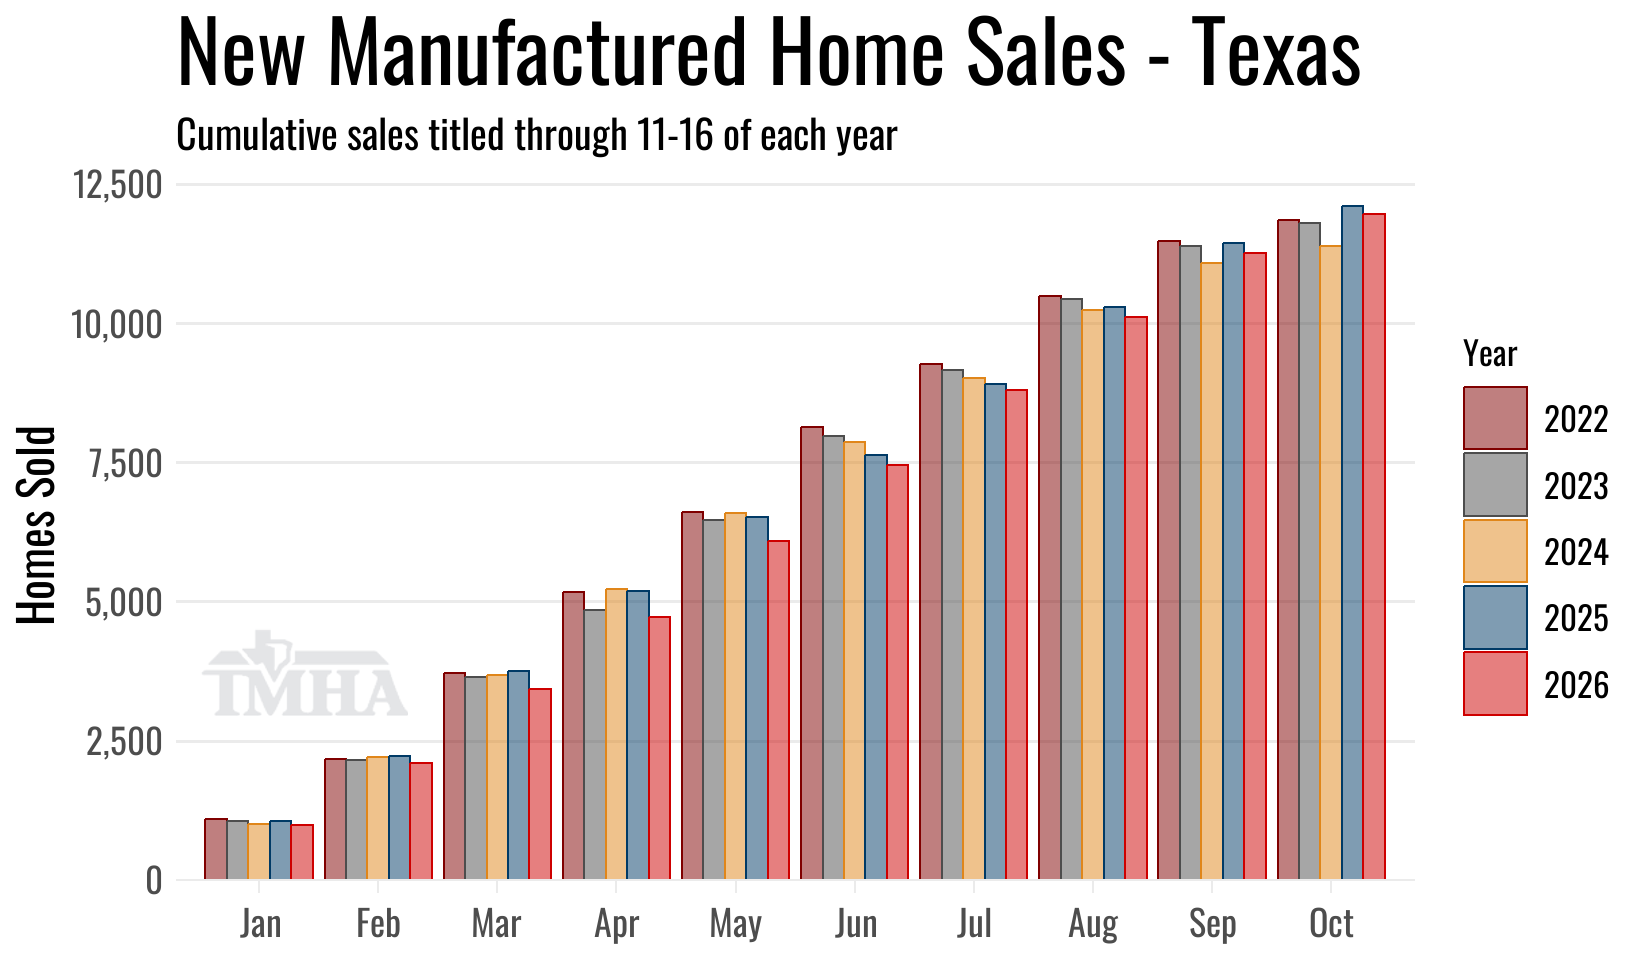
New home sales in 2026 are showing a 1.1% decline year-over-year for titles processed through this point compared to 2025.
Multi-section sales are up 4.9% year-over-year while single-section sales are down 9.8%.
As noted above, the titling phase shift inflated 2026’s year-over-year comparisons through the first half of the year, some of it simply pulling sales into June and July that a year ago would have been tallied as revisions to earlier months. With July through September now compared against post-change months, the slim lead 2026 carried through the summer has turned into a small deficit as the cadence effect washes out of the cumulative total.
We can also look at the statewide installation reports, which are running about 4% below last year’s pace year-to-date. That is a useful check on the titled total: the spring and summer lead was faster titling, not a surge of homes going into the ground.
| New Sales | Singles | Multis | Total |
|---|---|---|---|
| Total for 2026 titled to date: | 4,476 | 7,500 | 11,976 |
| Change from 2025 (%): | -9.8% | 4.9% | -1.1% |
| Change from 2025 (Units): | -487 | 353 | -134 |
TMHA Member’s Retailer Annual Sales Totals Report
New Home Characteristics
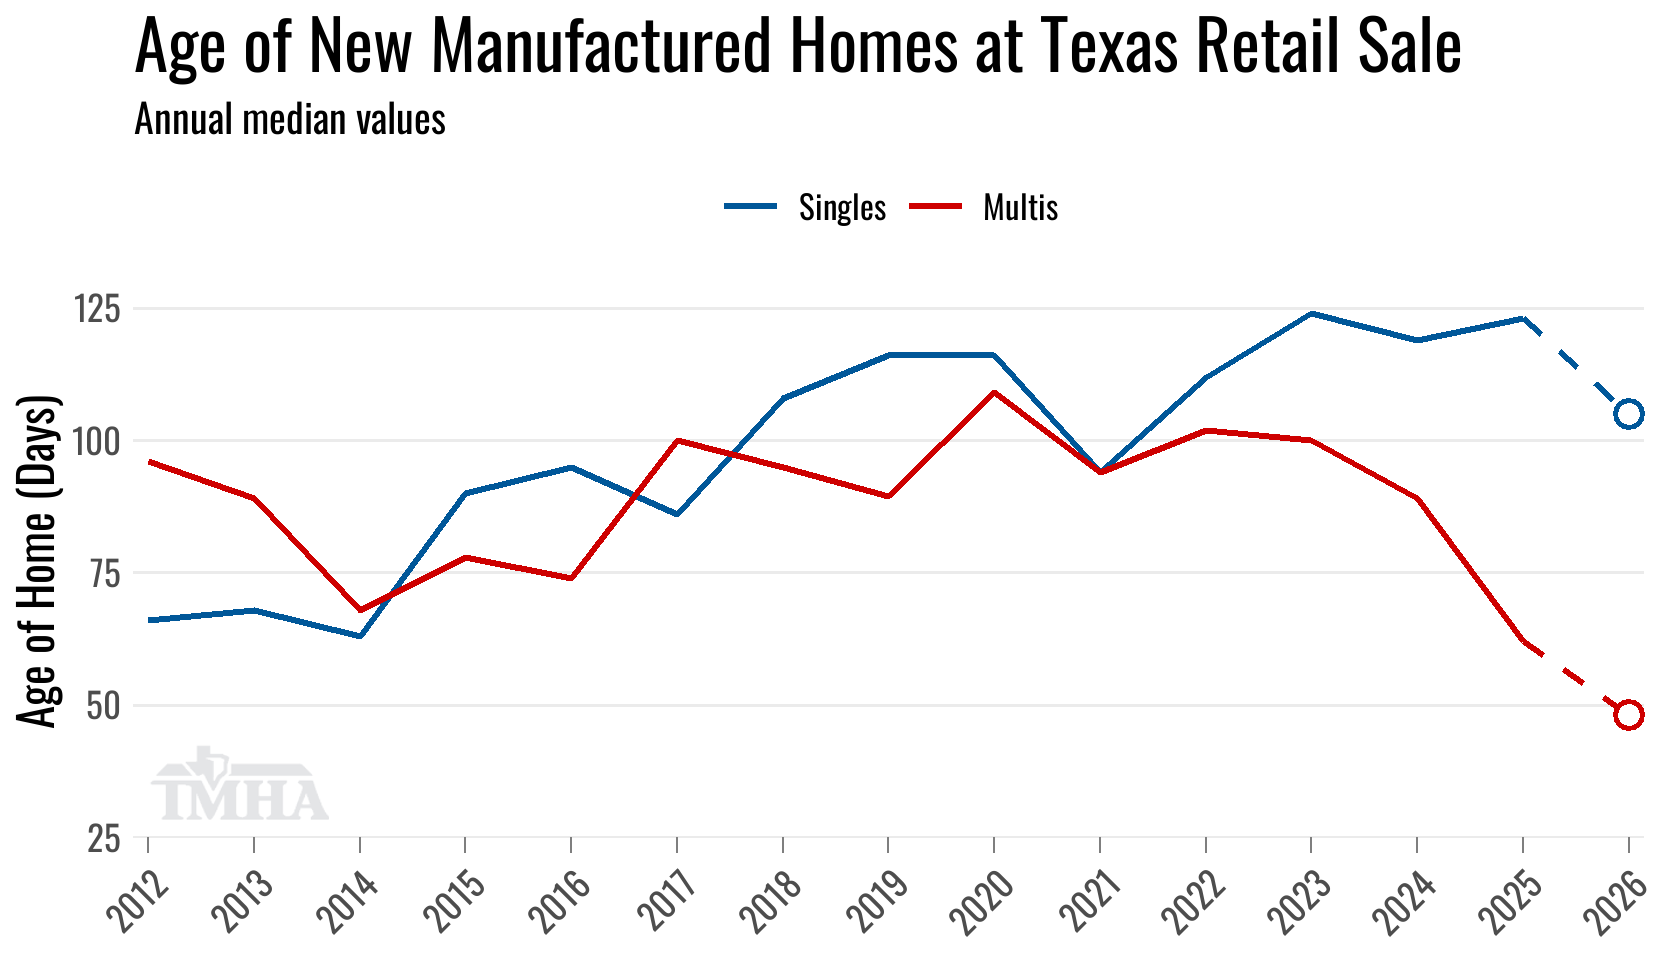
The shift in title cadence has really pulled down the median age of multi-section homes to the shortest amount of days in our records, and single-section homes are following, if less smoothly. August’s single-section median came in at 90 days, down from 108 in July and well below the 120-plus days that prevailed through 2025, while multi-section homes moved up to 55 days from 46. Year to date the medians stand at 105 days for singles and 48 for multis, which says single-section inventory genuinely is turning faster, even if the month-to-month path is noisy. Given how much the median has moved for multi-section homes, we suspect the change in date of sale guidance had an outsized effect on those home sale transactions, but the single-section market has also underperformed the multi-section market for several years now, so it makes sense those homes had been taking longer to turn.
| New Home Characteristics for 2026 | Singles | Multis | Total |
|---|---|---|---|
| Median Age of Home (Days): | 105 | 48 | 64 |
| Median Square Footage: | 1,080 | 1,699 | 1,475 |
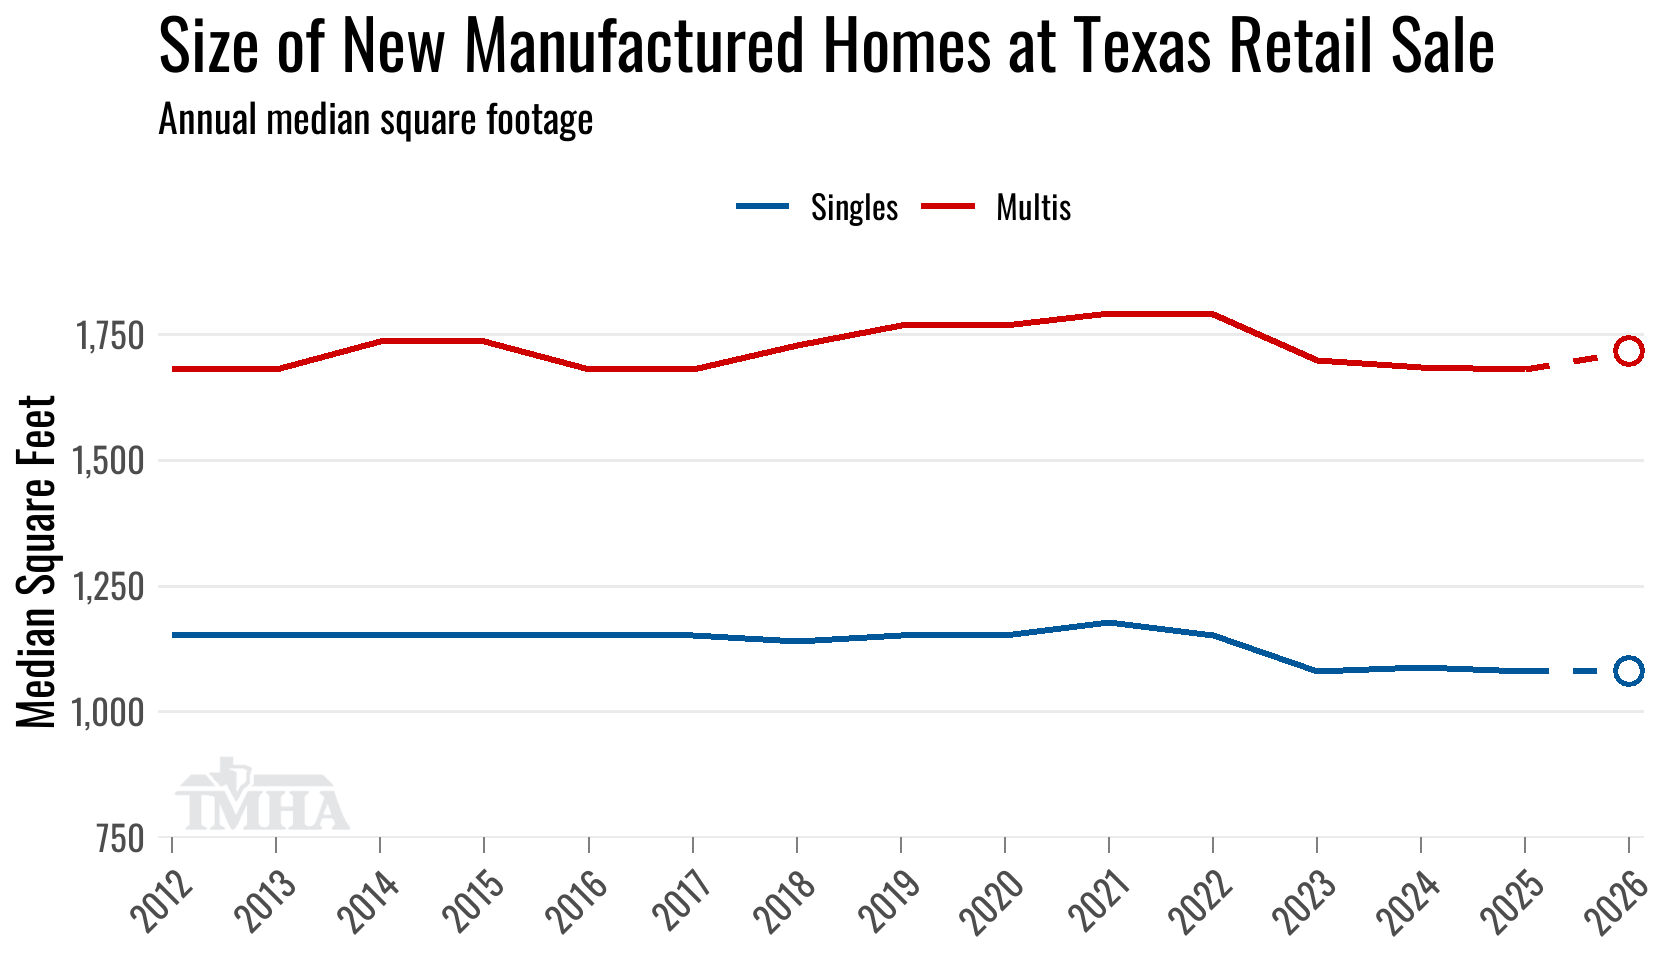
Beyond the age of homes at purchase, the square footage plot below shows a structural shift in Texans downsizing new home purchases when the affordability squeeze set in. The break is sharp and lands in a single year: both section types held their long-run size through 2022 and stepped down together in 2023. Multi-section medians moved from roughly 1,790 square feet to about 1,700, and single-section homes from roughly 1,150 to 1,080, where both have held since. Multis are running 1,699 so far this year, a modest uptick, though 2026 is a partial year and still settling.
Cash and Financed Purchases
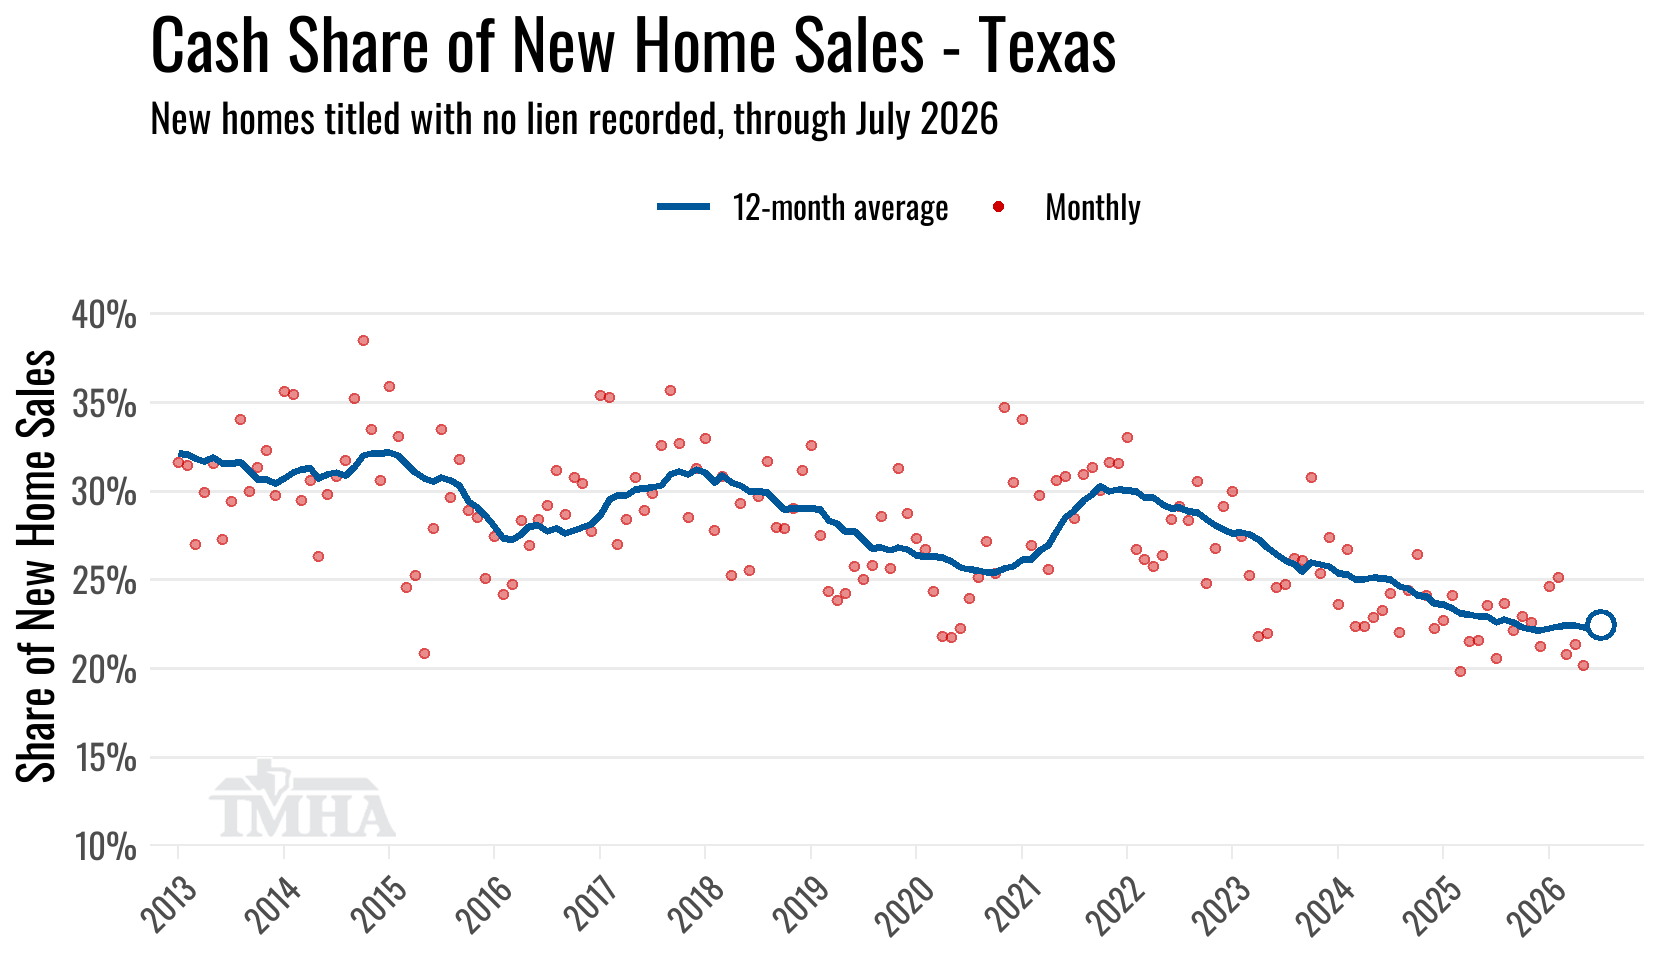
About 22% of new manufactured homes sold in Texas this year were bought without a loan, measured as the share of new-home statements of ownership issued with no lienholder recorded. That is in line with the 22% for the same months of 2025, and well below where it stood through most of the last decade: the twelve-month average was about 31% at the end of 2017 and is 22% through July 2026.
The financed side has been shifting toward land-home loans. Homes titled as real property with a lien, the closest thing in the title record to a home-and-land mortgage, made up 11.8% of new home sales through July, the highest share in records back to 2012 and well above the 6.6% of the same months a decade ago. The climb has not been a straight line: the share reached 11.0% in 2024 and dipped to 9.6% in 2025 before this year’s rebound.
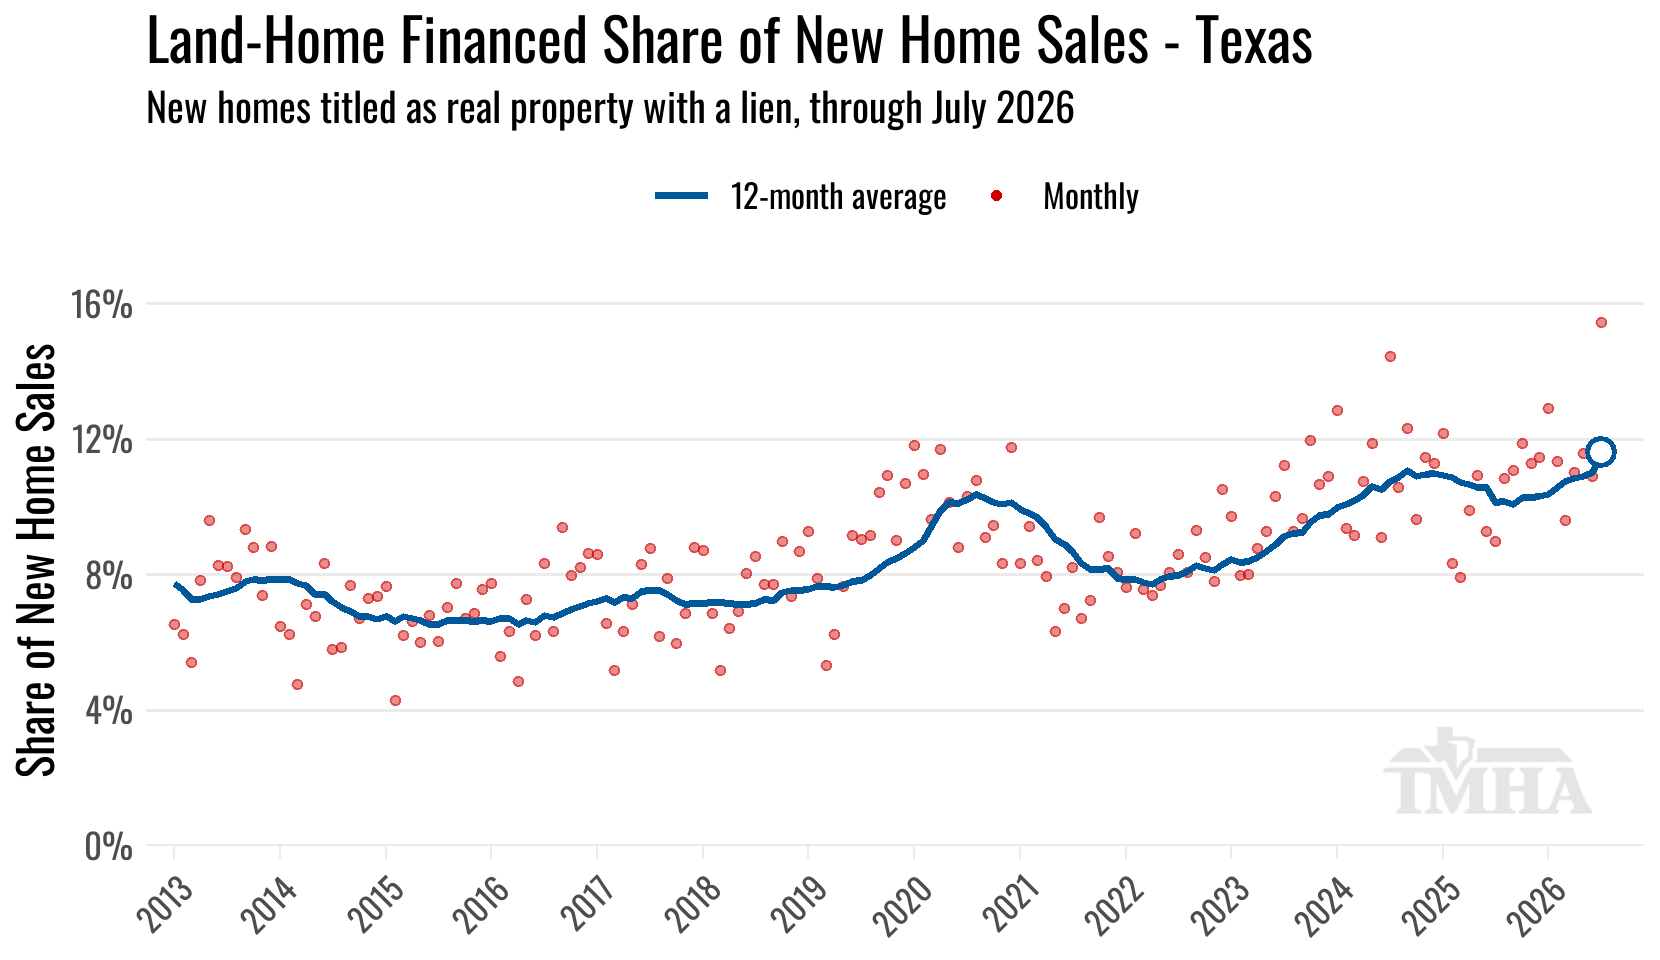
Part of both trends is product mix. Multi-section homes are financed more often than single-section homes, and they have grown from about 48% of new home sales in 2015 through 2017 to about 61% over the last two years. That shift accounts for roughly a seventh of the decline in the cash share and about a quarter of the rise in land-home financing. The rest is buyers of both home types financing more often, and the decline in cash purchases holds when sales made directly by manufacturers and purchases by companies are set aside.
Note: To compare years on equal footing, the plots count only homes whose first statement of ownership was issued within 90 days of the sale, and stop at the last sale month that has had the full 90 days. Cash purchases tend to be titled later than financed ones, so newer months would otherwise read low. A lien from any lender counts as financed.
New Home Placement Locations
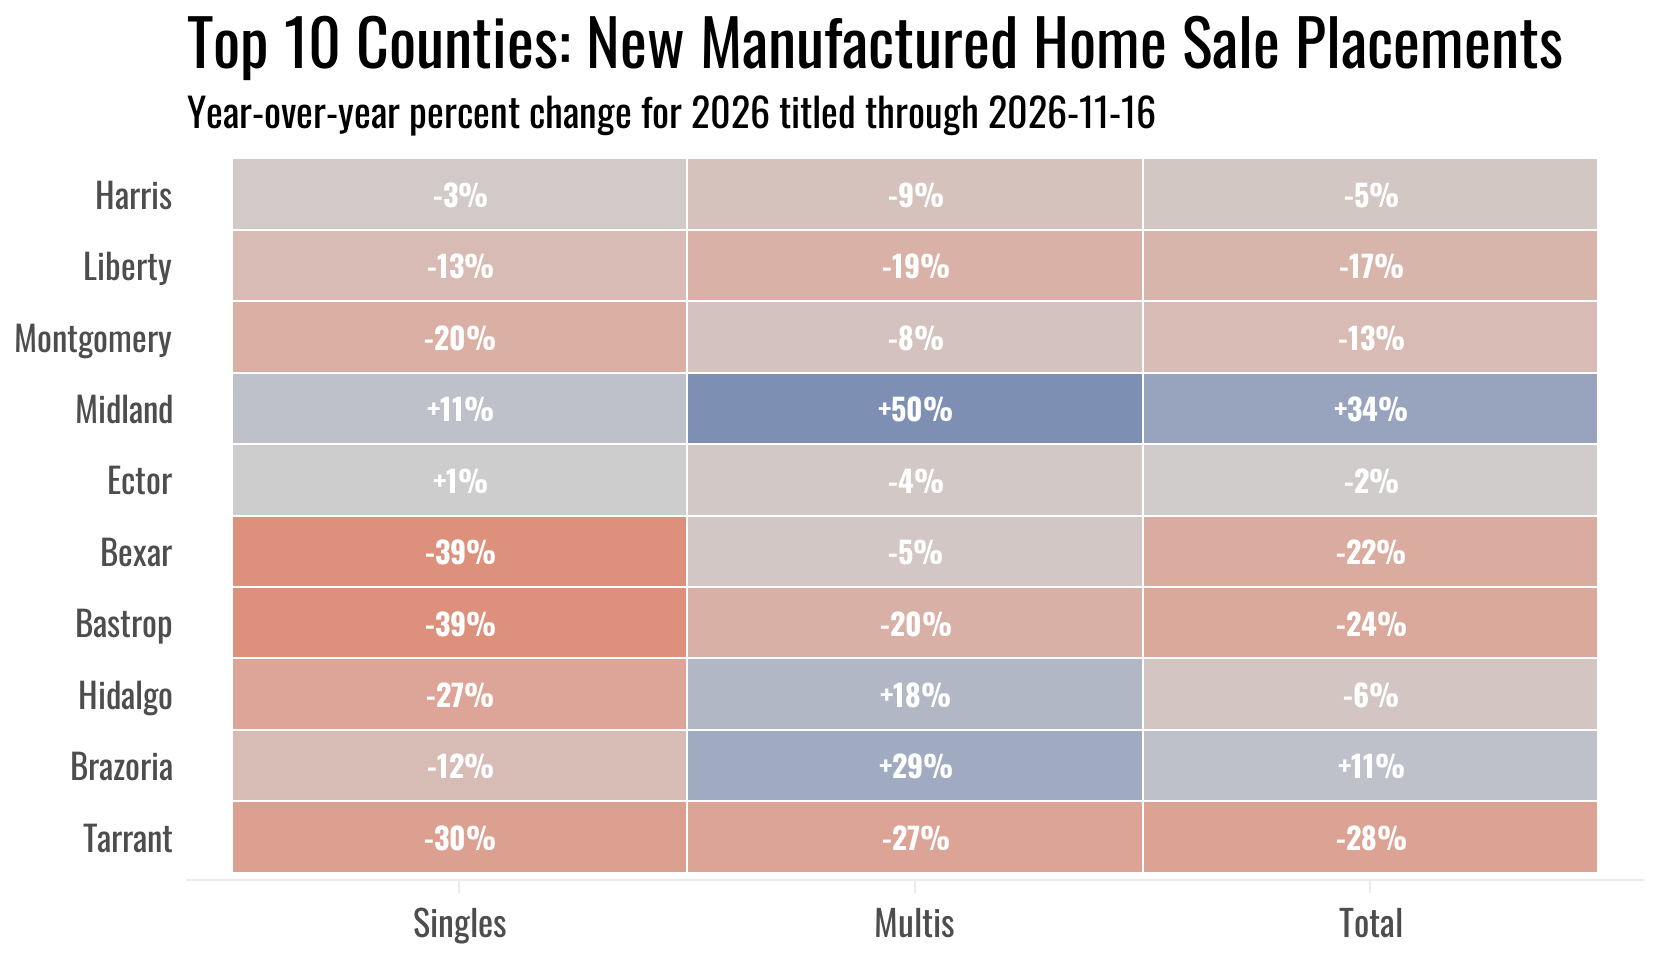
Here are the breakdowns in year-over-year changes for the top 10 counties in new home placements across home section types.
Midland, fourth in volume, leads the top 10 in year-over-year growth at +34.1%, well clear of Brazoria at +10.6%, the only other county ahead of last year’s pace through November 16. The remaining eight are behind, with Tarrant down 28.4%, Bastrop down 24.3% and Bexar down 22.4% showing the steepest declines, and Harris, the volume leader, off 5.3%.
TMHA Member’s Total Annual Retail Sales per County Report
Shipment Comparison
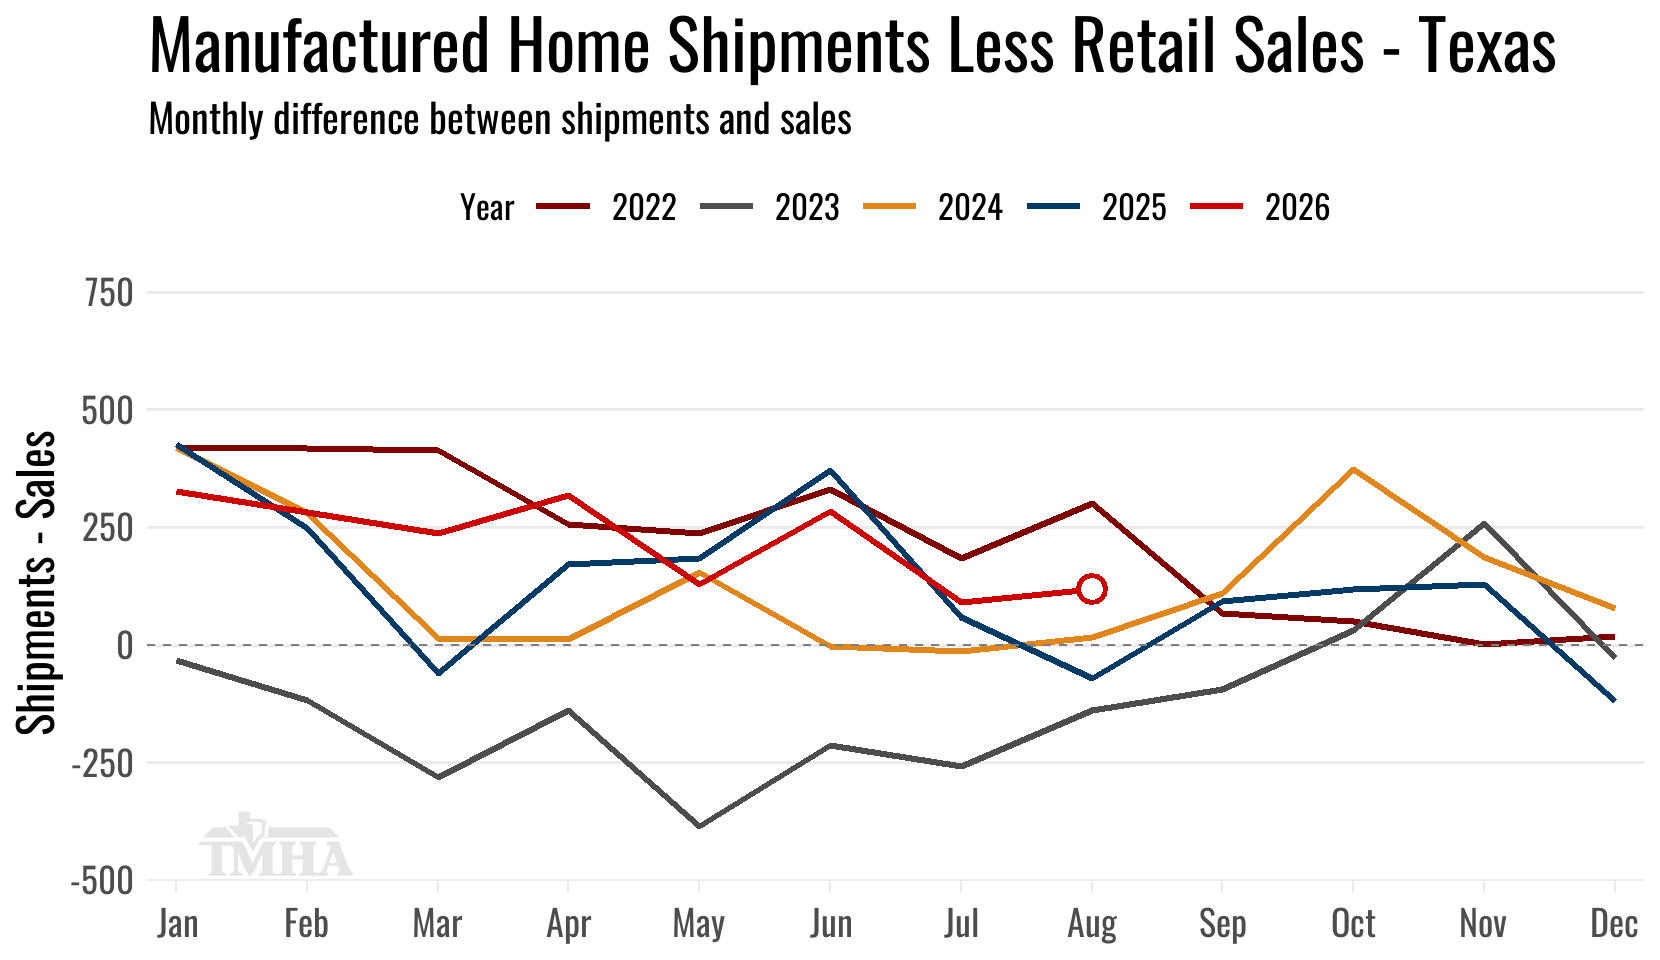
The gap between shipments and titled retail sales stayed narrow in August. July’s difference settled at 90 homes once its late titles arrived, and August’s 1,425 shipments ran 118 ahead of the 1,307 new home sales titled for the month. With August nearly complete that should close to roughly 80. September’s early look forecast leaves about a 140-home difference as September’s remaining titles arrive.
Moving Averages
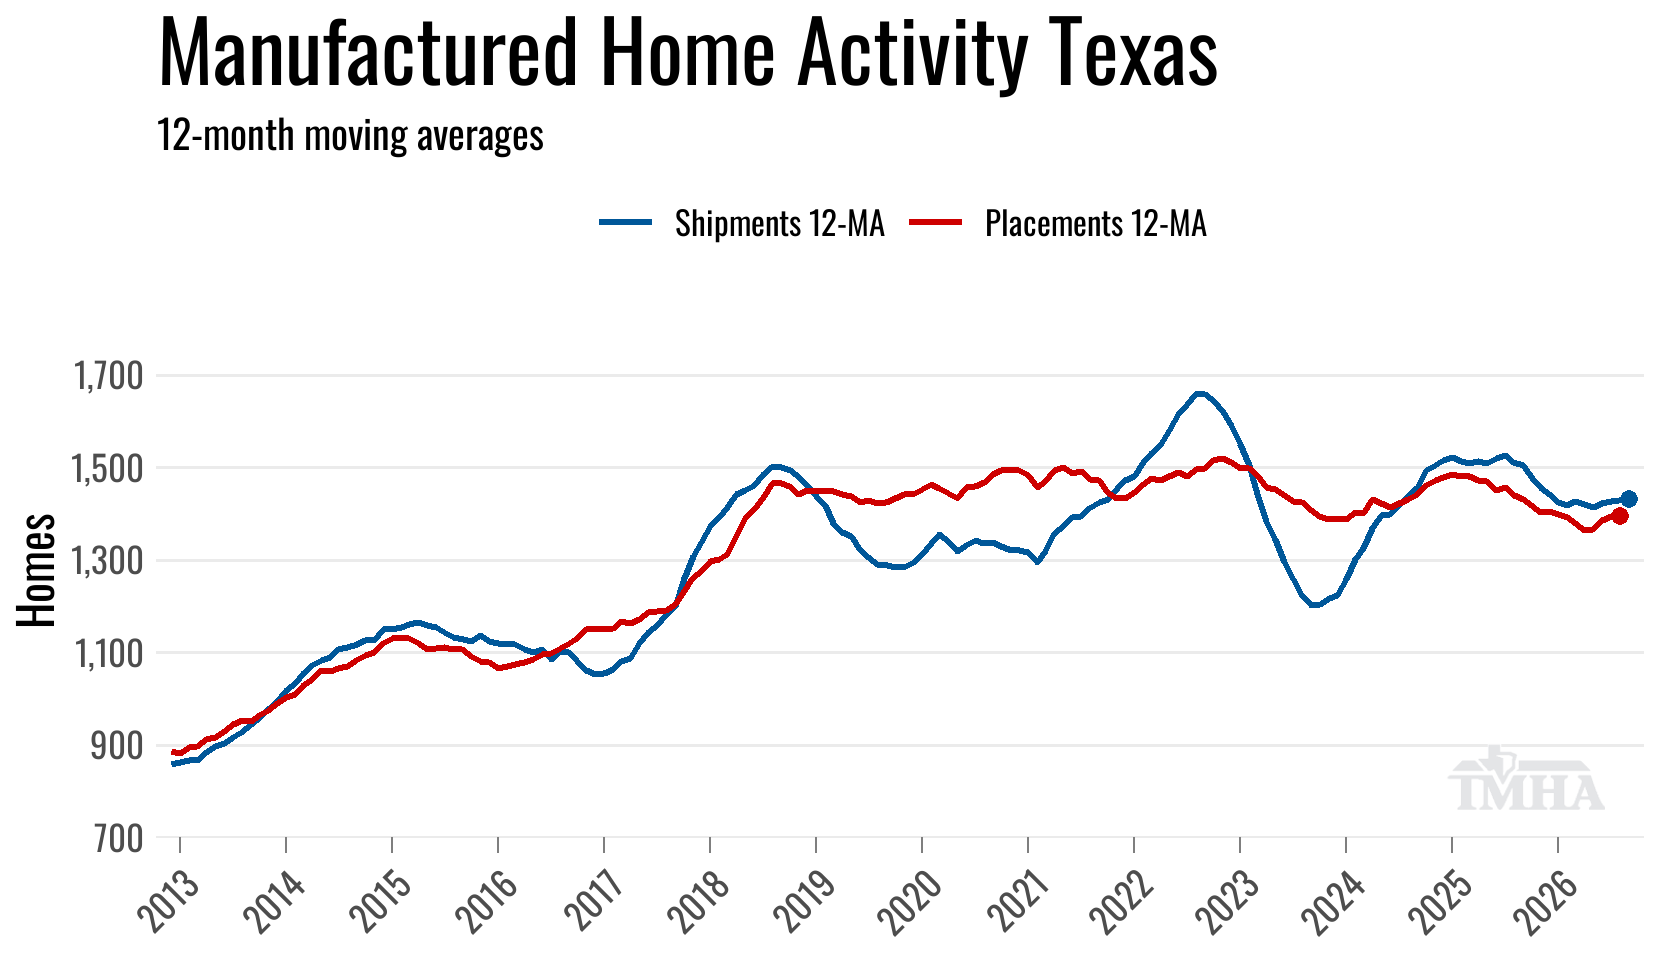
The plot below compares the 12-month moving average of shipments into Texas with placements (the first appearance of each new home in TDHCA records, by installation report or by title, whichever comes first). Placements counts a home once, whether it was sold at retail and titled or placed into a community’s inventory, so it is the broadest signal we have for new homes that are sited.
Some of the gap between the two lines is due to homes sold into Texas by retailers in Louisiana, Oklahoma and New Mexico, roughly 500 to 900 a year.
The shipments line runs through September and placements through August.
Used Homes
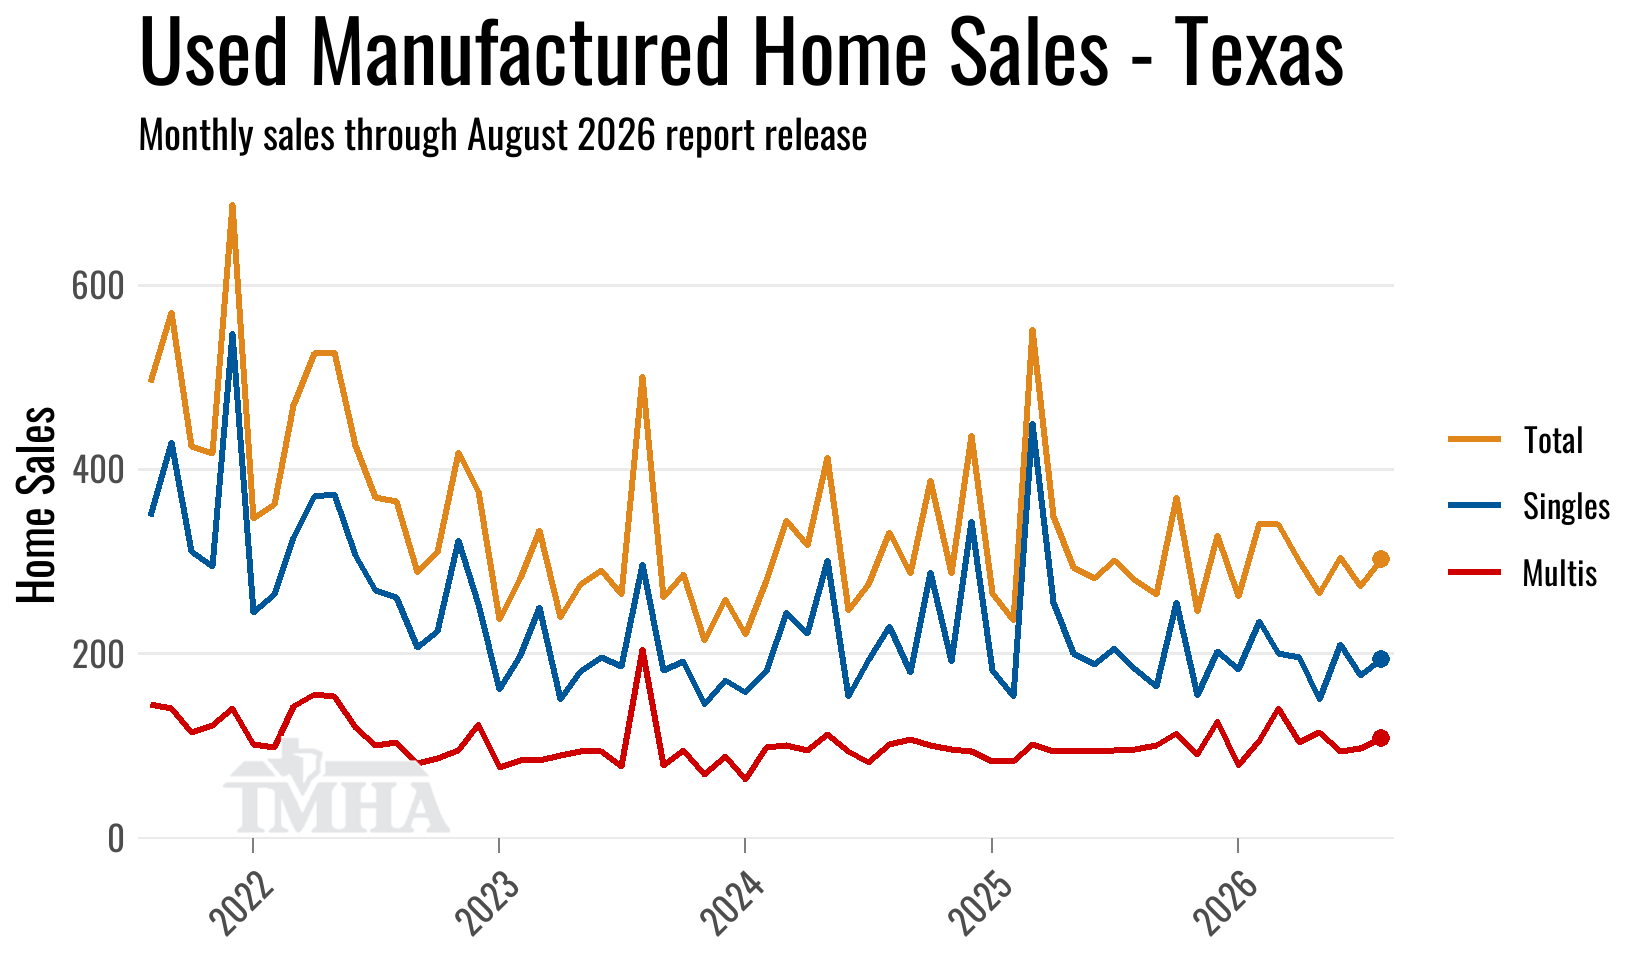
The used home retail sales data is noisy as it includes commercial purchases of park-owned homes after a manufactured home property is sold to a new buyer, but there was a clear downward trend in total transactions in the higher interest rate environment from 2022 through 2024 and have been roughly flat since.
| Used Sales | Singles | Multis | Total |
|---|---|---|---|
| Total for 2026 titled to date: | 1,750 | 974 | 2,724 |
| Change from 2025 (%): | -0.8% | 21.6% | 6.2% |
| Change from 2025 (Units): | -14 | 173 | 159 |
Revised Monthly Totals
Because titles continue to come in for past sales months, here are the prior 12 months and what their current sales totals are at this report release.
| New Sales Month | Singles | Multis | Total | (YoY%) |
|---|---|---|---|---|
| July 2026 | 483 | 875 | 1,358 | 6.9 |
| June 2026 | 486 | 861 | 1,347 | 22.2 |
| May 2026 | 512 | 856 | 1,368 | 2.2 |
| April 2026 | 482 | 809 | 1,291 | -10.2 |
| March 2026 | 534 | 808 | 1,342 | -12.0 |
| February 2026 | 428 | 679 | 1,107 | -4.7 |
| January 2026 | 399 | 587 | 986 | -7.1 |
| December 2025 | 525 | 768 | 1,293 | 6.1 |
| November 2025 | 420 | 714 | 1,134 | -13.9 |
| October 2025 | 506 | 816 | 1,322 | -5.7 |
| September 2025 | 522 | 766 | 1,288 | -3.8 |
| August 2025 | 542 | 937 | 1,479 | -2.5 |
| Used Sales Month | Singles | Multis | Total | (YoY%) |
|---|---|---|---|---|
| July 2026 | 176 | 97 | 273 | 14.2 |
| June 2026 | 210 | 94 | 304 | 23.6 |
| May 2026 | 150 | 115 | 265 | -2.9 |
| April 2026 | 196 | 104 | 300 | -6.0 |
| March 2026 | 200 | 140 | 340 | -30.2 |
| February 2026 | 235 | 106 | 341 | 50.2 |
| January 2026 | 183 | 79 | 262 | 6.1 |
| December 2025 | 202 | 126 | 328 | -17.6 |
| November 2025 | 155 | 91 | 246 | -10.2 |
| October 2025 | 256 | 113 | 369 | -2.4 |
| September 2025 | 164 | 100 | 264 | -6.0 |
| August 2025 | 183 | 96 | 279 | -14.4 |